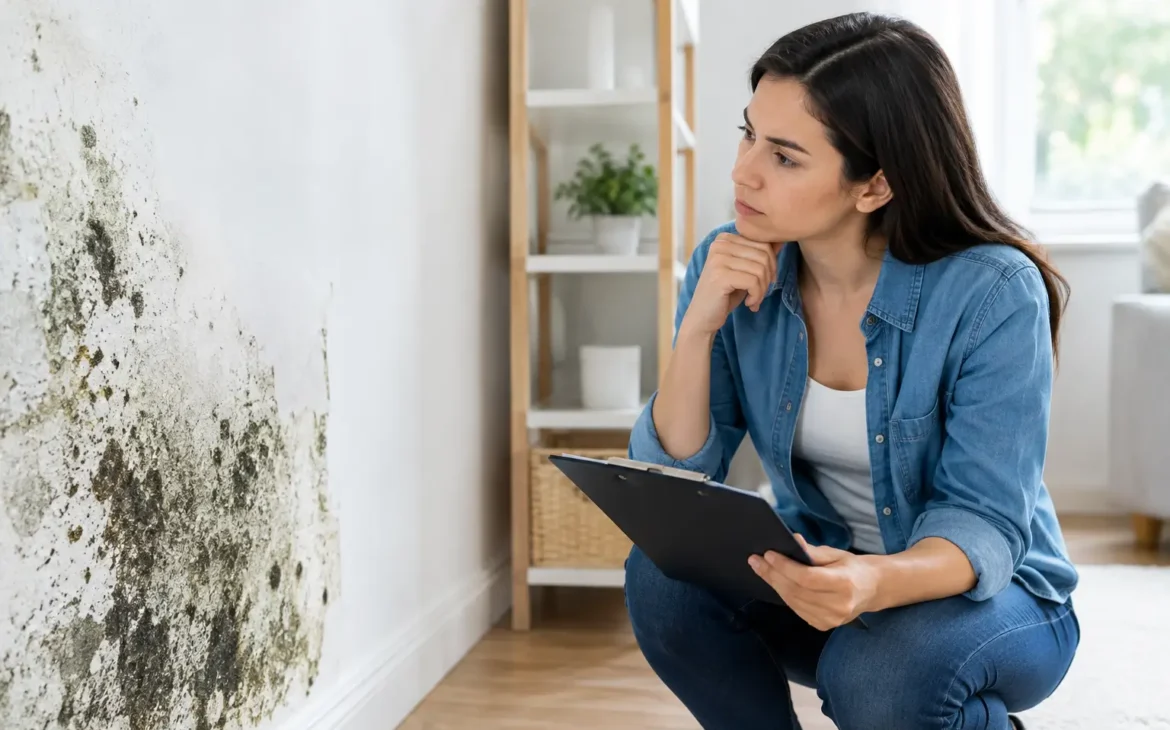
A small stain behind a bathroom vanity can become a much bigger problem once moisture has been trapped for weeks. The first question many property owners ask is: does insurance cover mold? The answer is sometimes, but coverage usually depends on what caused the mold, how quickly you responded, and the specific limits and exclusions in your policy.
For homeowners, landlords, and business owners, mold is rarely a standalone insurance issue. Insurers generally look at the water event behind it. If that event was sudden and covered, resulting mold remediation may be covered. If the mold developed from a slow leak, poor maintenance, humidity, or a known issue left untreated, the claim is much less likely to be approved.
Does Insurance Cover Mold From Water Damage?
Homeowners insurance may cover mold when it is the direct result of a sudden, accidental event that the policy covers. For example, a pipe bursts inside a wall, water damages the drywall, and mold appears before the area can be fully dried. In that situation, the policy may pay for portions of the water damage, mold testing, removal, and repairs, subject to your deductible and policy limits.
The key is the cause. A covered loss might include an accidental plumbing failure, an appliance supply line that suddenly breaks, or water damage from a covered storm claim. If the insurer accepts the underlying water claim, mold that results from that loss may fall within the coverage available for the claim.
That does not mean the entire bill will automatically be paid. Many home policies place a separate cap on mold, fungi, wet rot, or bacteria damage. A policy may provide a limited amount for cleanup even when the original water loss is covered. Higher limits may be available through an endorsement, depending on the insurer and property.
When Mold Is Usually Excluded
Insurance is designed for unexpected losses, not ongoing property maintenance. Mold claims are commonly denied when the damage stems from a gradual condition that a reasonable owner could have discovered or addressed.
Common examples include a slow plumbing drip under a sink, a long-term roof leak, recurring condensation around windows, unaddressed shower grout failures, and moisture caused by inadequate ventilation. Damage related to flooding is also generally excluded from a standard homeowners policy. Flood insurance is a separate product, and its treatment of mold can depend on the circumstances and policy terms.
Neglect can make a difficult situation even more expensive. If a homeowner notices water damage but delays repairs, an insurer may determine that the mold was preventable. Keep in mind that coverage language varies. One policy may offer limited fungi coverage, while another may exclude mold unless it results from a specifically covered event.
What a Mold Claim May Pay For
When coverage applies, the claim can extend beyond the visible mold. Depending on the policy and the scope of damage, eligible costs may include water extraction, professional drying, removal of contaminated drywall or flooring, mold remediation, testing when required, and repairs to restore the damaged part of the home.
Personal property damaged by a covered water event may also be considered under personal property coverage. However, furniture, clothing, electronics, and other belongings are subject to their own limits, deductibles, and valuation terms. Replacement cost coverage can make a meaningful difference compared with actual cash value coverage, which factors in depreciation.
Temporary living expenses may be available if a covered loss makes the home uninhabitable during repairs. This is often called loss of use coverage. It is not guaranteed simply because mold is found. The underlying event must be covered, and the damage must be serious enough to prevent normal occupancy.
For rental property owners, a landlord policy may address building damage and, in some cases, lost rental income following a covered loss. Business owners may need to look at commercial property coverage, business interruption coverage, and any relevant endorsements. Standard policies often have tighter mold limitations than owners expect, especially for older buildings or properties with prior water issues.
What to Do When You Find Mold
Your first priority is stopping the moisture source. Turn off the water if there is an active leak, move belongings away from the affected area when safe, and arrange for emergency mitigation. Waiting to see whether a stain gets worse can turn a manageable repair into a major remediation project.
Document the scene before extensive cleanup begins. Take dated photos and videos of the water source, affected rooms, damaged materials, and personal property. Save receipts for emergency services, dehumidifiers, plumbing repairs, and temporary protective measures. Do not discard damaged items until your insurer or adjuster advises you to do so, unless they create a health or safety concern.
Report a potentially covered loss promptly. Give the insurer clear facts about when you discovered the issue, what you believe caused it, and what steps you took to limit additional damage. Avoid guessing about the timeline. If the loss involves substantial contamination, structural materials, or health concerns, a qualified remediation professional can help define the scope of work.
A claim should not prevent you from taking reasonable steps to protect the property. Most policies require you to mitigate further damage. That may mean drying wet materials quickly, fixing a broken pipe, or arranging emergency water removal. It does not mean you should authorize a large restoration project without understanding the cost, the contractor’s scope, and your carrier’s claim process.
Read the Mold Language Before There Is a Problem
The declaration page tells you key limits, but the full policy explains the details. Look for terms such as fungi, wet rot, dry rot, bacteria, water damage, seepage, leakage, and repeated leakage. A separate endorsement may increase mold-related limits or broaden coverage in certain situations.
This review matters in both Illinois and Florida, though the risks can look different. Illinois homeowners may be concerned about frozen pipes, ice dams, and basement water problems. Florida property owners often face high humidity, wind-driven rain, roof concerns, and storm-related water intrusion. The right protection is not just about the state. It is about the home’s age, construction, plumbing condition, roof maintenance, location, and your comfort with the financial risk of a limited mold payout.
Before making changes, compare the cost of an endorsement with the limit it provides. A larger mold limit can be worthwhile for a home with prior moisture exposure, but it will not turn routine maintenance problems into covered claims. The best coverage strategy combines appropriate insurance limits with prompt repairs and preventative maintenance.
Practical Ways to Reduce Mold Risk
Mold prevention is largely moisture control. Repair plumbing and roof leaks quickly, run bathroom exhaust fans during and after showers, keep gutters and downspouts moving water away from the foundation, and inspect under sinks and behind appliances regularly. In humid spaces, a dehumidifier and proper airflow can help prevent condensation from becoming a recurring issue.
Pay close attention after any water event, even one that seems minor. Drywall, insulation, subflooring, and cabinets can retain moisture out of sight. Fast drying can protect both the property and a potential insurance claim, because it shows that you acted to limit the damage.
Get Advice Before a Coverage Gap Becomes a Claim
Mold coverage is one of the areas where policy details matter more than a quick yes-or-no answer. An independent agent can help you compare carriers, review sublimits, and identify whether an endorsement fits your property and budget. LS Premier can help homeowners and business owners evaluate coverage choices without being limited to one insurer’s policy options.
A little policy review now can make a stressful water loss easier to handle later. Know your mold limit, maintain the parts of your property that keep water out, and act quickly when moisture appears.